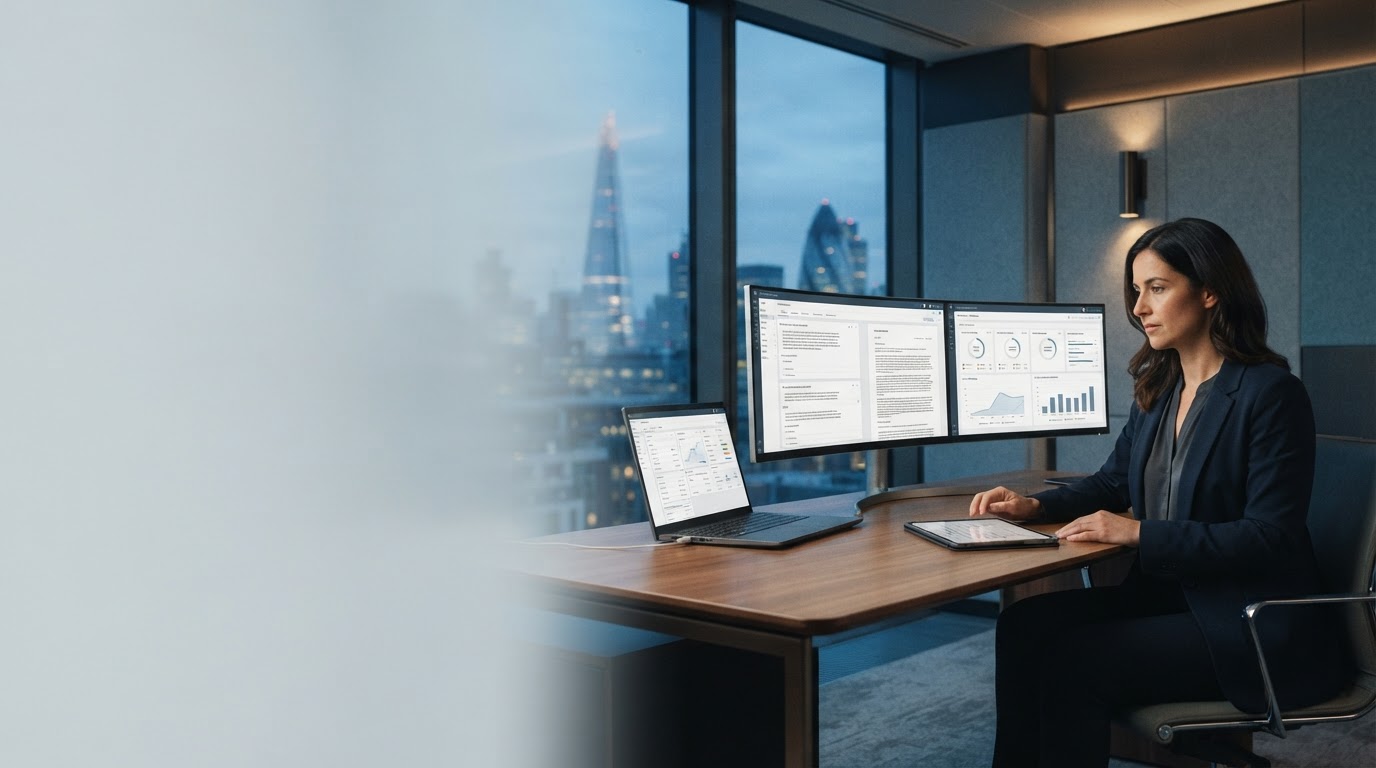
AI-driven data intelligence
Retrial processes large volumes of market data on a continuous basis and converts it into risk-adjusted performance metrics, so decisions are grounded in evidence rather than sentiment.
The dashboard surfaces drawdown, volatility-adjusted returns and model confidence intervals, refreshed on a daily cycle rather than real-time noise.
Data vs. insight
The Retrial engine
No single model is treated as final. Retrial continuously re-examines its own output against new data, which is where the platform takes its name.
01 — Real-time analysis
Market, on-chain and order-book data are ingested and normalised continuously, allowing the system to detect structural shifts rather than isolated price moves.
02 — Predictive modelling
Models are trained to identify multi-variable correlations across assets and timeframes that are difficult for a human analyst to track manually.
03 — Risk mitigation
Position sizing and exposure limits follow fixed, documented rules, so risk management does not depend on discretionary judgement during periods of stress.
Transparency by design
Reporting is not generated on request or adjusted retrospectively. Each cycle produces a fixed record of positions, returns and risk exposure at the point it was captured.
Applied use
Portfolio diversification
Retrial monitors correlation between holdings as it shifts over time, flagging when a portfolio that appears diversified is in practice exposed to a single underlying risk factor.
Automated rebalancing
When exposures drift beyond pre-set thresholds, the system rebalances according to fixed rules, which limits drawdown during periods of sudden market movement without requiring manual intervention.
Historical backtesting
Model logic is tested against historical market cycles, including prior periods of high volatility, so performance characteristics are understood before capital is allocated.
Frequently asked
Data in transit and at rest is encrypted using industry-standard protocols. API keys used for exchange connections are stored with restricted, read-only permissions wherever the exchange supports this, and withdrawal access is never requested.
Data is sourced through direct API integrations with established exchanges and market data providers. Each feed is validated against at least one secondary source before being used in model calculations, reducing the risk of relying on a single point of failure.
Risk-management protocols are deterministic and documented: position limits, exposure caps and rebalancing triggers follow fixed rules rather than opaque discretionary logic. Predictive components are retrained on a scheduled basis, and the criteria for retraining are recorded in your daily reports.
Request access to see live daily reporting and historical backtesting for a sample portfolio configuration.
Request platform accessNo payment details are required to request access. You will receive a sample daily report within the evaluation period.